Plastic Waste Pyrolysis Oil Market Opportunities Rise Through Demand for Alternative Feedstocks and Energy Resources
Asia-Pacific is emerging as a major growth region for the plastic waste pyrolysis oil market. The region combines large volumes of plastic waste, expanding manufacturing industries, growing petrochemical capacity, and increasingly stringent waste-management policies. These conditions are creating an attractive environment for advanced recycling investments.
The global market is projected to reach USD 6.37 billion by 2035 from USD 1.60 billion in 2025, registering a CAGR of 14.8%. Asia-Pacific is forecast to grow at the fastest regional CAGR of approximately 16.3% through 2035.
China represents an important market because of its large manufacturing base and significant plastic consumption. The development of domestic advanced recycling capacity is helping create new pathways for difficult-to-recycle plastic waste. Integration with existing petrochemical infrastructure can further strengthen the economics of pyrolysis projects.
India is another promising market. Increasing enforcement of Extended Producer Responsibility requirements is encouraging companies to improve plastic waste collection and recycling. The availability of post-consumer waste combined with expanding industrial infrastructure creates opportunities for decentralized and modular pyrolysis facilities.
Japan and South Korea also provide favorable conditions because of their advanced technology capabilities, mature chemical industries, and focus on resource efficiency. Refinery integration and technology development are helping these countries explore the use of pyrolysis oil as an alternative feedstock.
Waste plastics remain the dominant raw-material segment globally. The availability of polyethylene and polypropylene packaging waste makes these materials particularly suitable for pyrolysis. However, efficient sorting and preprocessing are essential to maintain consistent plant performance.
Fuel applications currently represent the largest source of demand, while chemical applications are growing faster. Asian petrochemical producers can potentially use upgraded pyrolysis oil to support recycled-content polymer production, creating a connection between waste management and high-value chemical manufacturing.
Investment in technology is also increasing. Continuous reactors, catalytic systems, automated sorting, and digital monitoring can help improve plant efficiency. Modular facilities may be especially useful in regions where waste collection is fragmented and transportation costs are high.
Challenges include feedstock quality variation, financing requirements, regulatory uncertainty, and limited infrastructure in some markets. Establishing reliable waste-collection systems will be essential for maintaining stable plant utilization.
Despite these challenges, the combination of rising plastic waste generation, EPR implementation, industrial capacity, and circular-economy policies provides a strong foundation for growth. Asia-Pacific is therefore expected to remain one of the most important expansion areas for the Plastic Waste Pyrolysis Oil Market through 2035.
Categorias
Leia Mais
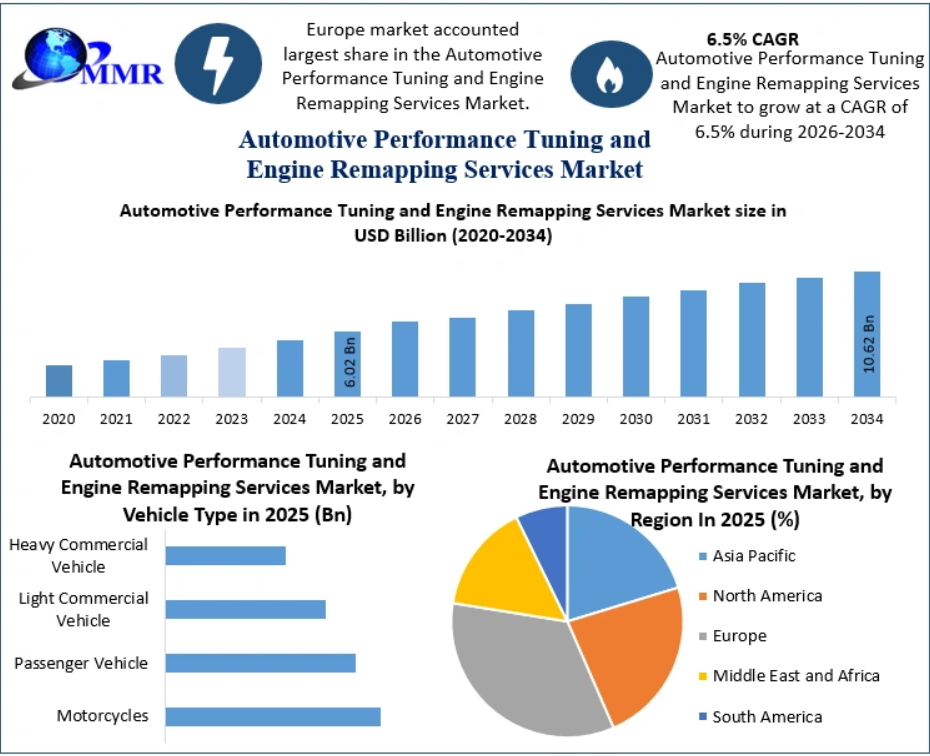
Automotive Performance Tuning and Engine Remapping Services Market Overview The Automotive Performance Tuning and Engine Remapping Services Market report provides an in-depth analysis that is required to make informed industry decisions and develop strategic growth plans. Regardless of the production method or cost structures, the Automotive Performance Tuning and...
Manufacturing processes play a major role in determining how engineering polymers are adopted across industrial applications. Injection molding is particularly important because it enables manufacturers to produce precise, complex components efficiently at commercial scale. The Polyphenylsulfone Market includes injection molding, extrusion, film, and fiber grades, with Injection Molding Grade...
Carbon fiber tapes are lightweight, high-strength composite materials made from continuous carbon fibers combined with a polymer matrix, offering excellent strength-to-weight performance and dimensional stability. The Carbon Fiber Tapes Market size was valued at US$ 3.86 Billion in 2025 and is projected to reach US$ 11.75 Billion by 2033, growing at a CAGR of 14.93% during...
" According to the latest report published by Data Bridge Market Research, the On Premise Time Tracking Software Market As per Data Bridge Market Research Analysis the Global on premise time tracking software market size was valued at USD 2.13 billion in 2025 and is expected to reach USD 9.25 billion by 2033, at a CAGR of 20.10% during the forecast period On Premise Time Tracking...